Cost & Insurance
How to Document Water Damage for an Insurance Claim (Photo & Receipt Checklist)
Claims are won or lost on evidence gathered in the first hour. Here is exactly what to photograph, what to keep, and what adjusters actually look at.
The short answer
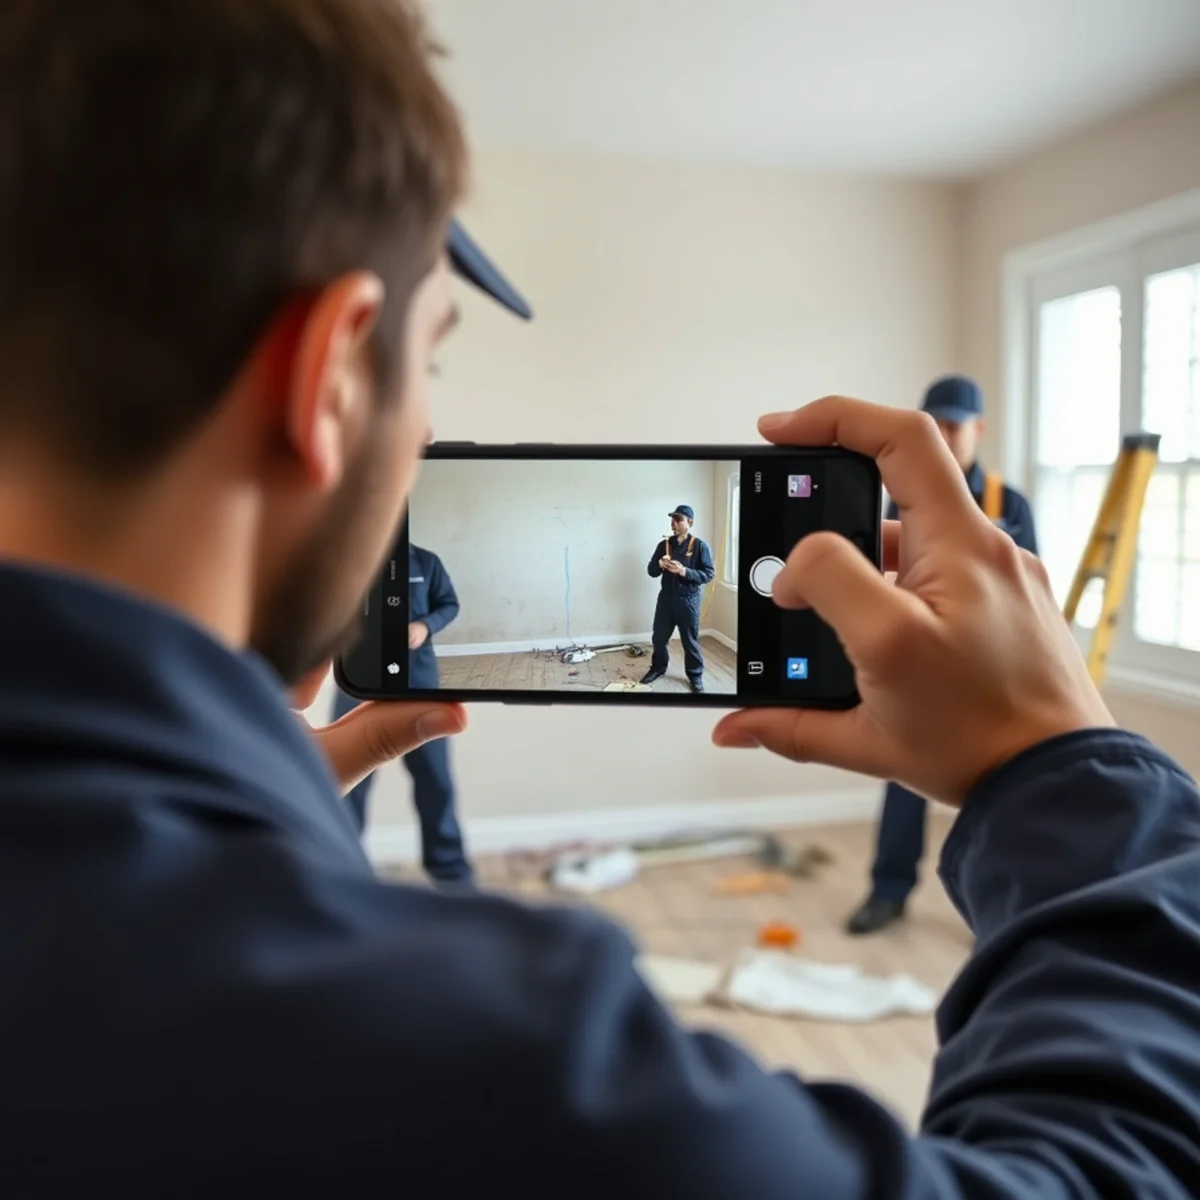
Photograph everything before you touch anything: wide shots of each room, close-ups of the source, and the water line on the walls. Keep whatever failed — the burst hose, the cut section of pipe. Then start a single folder for every invoice, receipt and dated call log.
Adjusters are not adversaries, but they are working from evidence rather than from your account of what happened. What you photograph in the first hour frequently determines what gets paid.
The good news is that the whole job takes about fifteen minutes and needs nothing but your phone.
Dealing with this right now?
Crews dispatched within 60 minutes — on-site in 60–90 minutes, anywhere in Fullerton. Call and we will talk you through the first two minutes while a crew is dispatched.
- 60-minute dispatch, anywhere in Fullerton
- IICRC-aligned · licensed & insured
- Direct insurance documentation
Before You Touch Anything
This is the rule that matters most. Once cleanup begins, the evidence is gone and it cannot be recreated.
That does not mean leaving water on the floor while you take pictures for an hour. It means: shut the water off, then spend ten minutes documenting, then start moving things.
The Photo Checklist
Work outward from the source. Take far more than you think you need — nobody has ever regretted having too many photographs of a loss.
- The source itself, close up: the failed pipe, the split hose, the water heater, the ceiling entry point. Include the physical failure, not just the water.
- Wide shots of every affected room from the doorway, so the extent is obvious.
- The water line on walls, cabinets and furniture. This is the single most useful image for an adjuster — it establishes how high the water stood and sets the replacement scope.
- Flooring at doorways and thresholds, showing where water crossed into other rooms.
- Contents on the floor before you lift them: boxes, rugs, furniture bases, the bottom of cabinets.
- Anything already showing damage — swollen laminate, lifted vinyl, stained drywall, cupped hardwood.
- Serial and model numbers of any damaged appliance, and the manufacture date label on a failed water heater.
Video Is Better Than Stills For The Walkthrough
Take one continuous video walking through the affected areas, and narrate it out loud.
Say the date and time. Say what room you are entering. Point out what you are looking at and where the water came from. Show the water line as you pass it.
This is more persuasive than a folder of stills because it shows spatial relationships — how the rooms connect and how far the water travelled — and because narration timestamps your knowledge of the event.
If it is a storm loss, get the weather audible. Evidence of an active event is exactly what separates a covered wind loss from a denied maintenance claim.
Keep The Physical Evidence
Do not throw away what failed.
The burst washing machine hose, the section of pipe the plumber cut out, the failed supply connector — bag it, label it with the date, and keep it until the claim closes.
This matters because the most common denial reason is gradual damage. A hose with a clean split is physical proof of a sudden failure. A photograph of a corroded pipe with a single pinhole tells a different story than a homeowner's description of one.
The same applies to damaged contents. Do not dispose of anything until the adjuster has seen it or you have photographed it thoroughly, including serial numbers and any purchase documentation you can find.
The Paper Trail
Start a single folder — physical or digital — the day it happens, and put everything in it.
- The claim number and the adjuster's name, direct line and email
- A dated log of every call and what was said, including with your carrier
- Every invoice and receipt: the plumber, the restoration company, any emergency purchases
- Hotel and meal receipts if you had to relocate — that is your additional living expenses claim
- Any prior maintenance records: water heater servicing, roof inspections, sewer camera reports
- The written scope of work and the moisture map from your restoration company
- Daily drying logs showing equipment placed and readings taken
What Your Restoration Company Should Be Producing
Your own documentation is half of it. The other half comes from the professionals, and you should expect to see it rather than have to ask.
A moisture map: which materials were affected, with baseline readings and a dry standard taken from an unaffected part of your own house.
Daily drying logs: equipment placed, temperature, relative humidity and material moisture content at marked points. This is what proves the property reached a dry standard, and it is the answer if a mold question arises later.
A line-item scope of work written in the estimating format your carrier already uses, so the adjuster can review it directly rather than translating.
Photographs from the professional inspection, including thermal images showing moisture behind surfaces you cannot see.
If a company cannot produce those, that is worth knowing before they start.
Two Things People Get Wrong
The first is waiting to document until the adjuster schedules a visit. By then the water is gone, the drying is underway, and the most persuasive evidence no longer exists. Document immediately; the adjuster's visit is a second record, not the first.
The second is over-cleaning before the inspection. There is a real difference between preventing further damage — which your policy requires — and tidying away the evidence. Extract the water and start drying, absolutely. Do not throw out the ruined carpet, repaint the ceiling, or dispose of damaged contents before anyone has seen them.
The Mistakes That Cost People Money on Otherwise Valid Claims
Most reduced settlements are not denials on the merits. They are valid claims that lost value somewhere in the handling, usually in the first week and usually through something that seemed helpful at the time.
Every one of these is avoidable, and none of them requires an attorney or a public adjuster to avoid.
- Discarding damaged contents before the adjuster has confirmed they do not need to inspect them. Once it is gone, it is unverifiable.
- Giving a recorded statement early and speculating about how long the leak had been going. Speculation about duration is what gradual-damage denials are built from.
- Cleaning up thoroughly before photographing. Mitigation is required, but photographs come first — it takes four minutes.
- Accepting the first estimate without comparing scope. Read what is actually listed rather than the total, and check whether it includes the drying equipment days you were billed for.
- Failing to keep receipts for hotel, meals and laundry during displacement. Loss of use pays those, but only against documentation.
- Not requesting a copy of your own policy in full. You are entitled to it, and the endorsements page frequently contains coverage the adjuster did not mention.
Frequently asked
As soon as you reasonably can — the same day is ideal. Policies require prompt notice, and prompt reporting is also the strongest defence against a gradual-damage denial. Starting emergency mitigation before you call does not prejudice the claim; your policy expects you to prevent further damage.
Document what remains and be straightforward about the sequence. Keep any physical evidence you still have, and get a professional moisture assessment — meters will still show what was affected even after surfaces look dry. Your restoration company's readings become the primary evidence in that case.
Yes. Their documentation starts when they arrive; yours starts when it happened. That gap is often the most important hour of the loss, and adjusters give weight to contemporaneous homeowner evidence of the event itself.
The bottom line
Ten minutes with your phone before you touch anything. Wide shots, the source, the water lines, the contents.
Then keep what failed, keep every receipt, and expect your restoration company to produce a moisture map and daily drying logs.